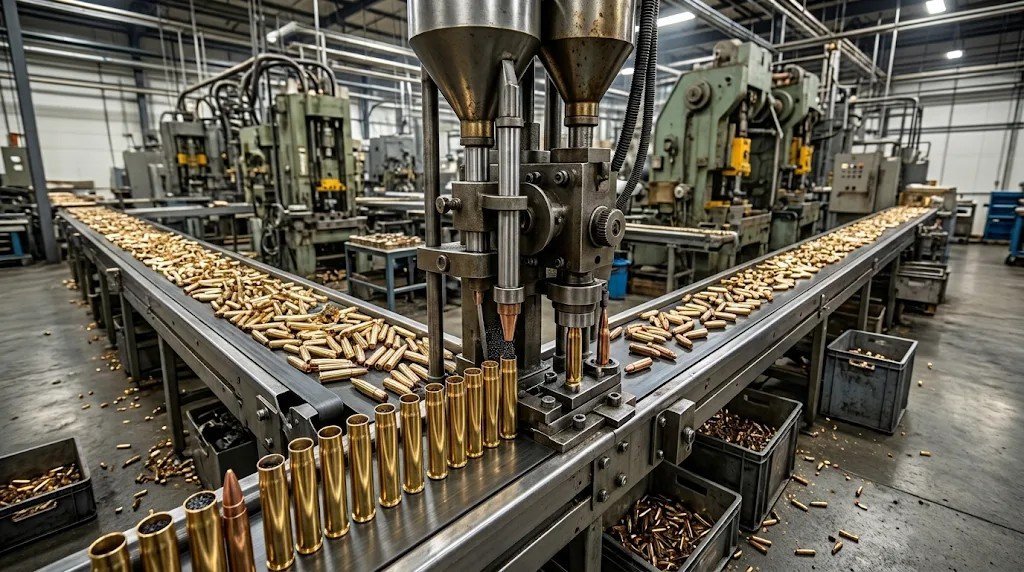
An ammunition assembly line cost assessment depends on the boundaries of the proposed investment and the obligations included in the project. A headline equipment figure cannot represent the financial commitment associated with premises, professional assessments, organizational preparation, documentation, and ongoing business overhead.
A useful evaluation separates confirmed expenditure from provisional allowances and unresolved assumptions. This distinction helps management understand what a budget covers and where further evidence is required.
The following overview addresses financial governance and general industrial investment considerations. It excludes equipment selection, manufacturing configurations, production specifications, and supplier procurement instructions.
A meaningful budget begins with a written description of the investment scope and the responsibilities attached to each expenditure category.
Different proposals may use similar terminology while covering substantially different obligations. One estimate might address a limited contractual deliverable, while another includes broader professional services or administrative support. Comparing their totals without examining these boundaries can produce misleading conclusions.
Management should distinguish the initial investment from recurring business expenses. Property commitments, independent reviews, staff administration, insurance, and document management may follow different payment schedules and approval processes.
Every budget category should have a clear purpose, an accountable owner, and an identified basis for the estimate. Unverified assumptions should remain visible throughout the review.
The financial implications of a proposed premises extend beyond the property agreement itself.
Before committing to a location, decision-makers need qualified assessments of its suitability for the intended business activity. Building condition, environmental considerations, surrounding land use, accessibility, and contractual restrictions can influence whether further development is justified.
The budget should recognize the professional work needed to investigate these matters. A property that appears commercially attractive may carry unresolved obligations that change the overall investment assessment.
Assessment findings should feed back into the financial model. Treating professional reviews as a formality can leave management working with a budget that no longer reflects the project.
Initial expenditure and recurring overheads serve different purposes and should be reviewed separately.
The following framework organizes general business expenditure without assigning monetary figures.
|
Budget category |
Financial consideration |
Management review |
|---|---|---|
|
Property commitments |
Occupancy obligations and associated expenses |
Confirm contractual boundaries |
|
Professional assessments |
Independent advice and documented reviews |
Define the required scope |
|
Organizational preparation |
Recruitment, administration, and role development |
Assign responsibility |
|
Documentation |
Record control and information management |
Establish ownership |
|
Insurance |
Coverage appropriate to the business |
Obtain qualified advice |
|
Recurring overheads |
Continuing administrative and property expenses |
Review cash-flow assumptions |
Separating these categories makes it easier to identify whether a proposal describes a limited purchase or a broader business investment.
Contract wording can materially affect the expenditure a business ultimately carries.
Payment obligations, exclusions, responsibilities for revisions, and ownership of deliverables should be understood before commitments are approved. Ambiguous wording can create disagreement over whether additional work falls within the original scope.
When reviewing a proposal associated with Yeter Makina, financial conclusions should rely on documented contractual information. Statements about included services, support arrangements, or commercial obligations require verification rather than inference from the brand name.
A sound review also records dependencies. An estimate that assumes a suitable building, available personnel, or completed assessments should identify those assumptions explicitly.
An early budget is a decision-support document whose reliability depends on the evidence behind its assumptions.
Management should distinguish confirmed commitments, provisional estimates, and items awaiting professional assessment. Combining these into one undifferentiated total conceals uncertainty and makes later revisions harder to explain.
A contingency allowance should have a documented rationale. It should not become a substitute for investigating known gaps or clarifying contractual responsibilities.
Cash-flow planning also deserves separate attention. The timing of payments and continuing overheads can affect financial resilience even when the overall investment remains within the approved budget.
A consistent review process helps management understand why the financial outlook changes as the project develops.
Each revision should identify the changed assumption, supporting evidence, financial implication, and approving person. This creates an understandable record of decisions and prevents outdated estimates from circulating as current information.
Budget reviews should also consider whether the proposed investment remains aligned with the business purpose. Expenditure already incurred should not automatically justify further commitments when material questions remain unresolved.
An ammunition assembly line cost discussion is most useful when it clarifies scope, uncertainty, and ongoing obligations. Any assessment involving Yeter Makina should use verified information and qualified financial review to support an informed investment decision.
